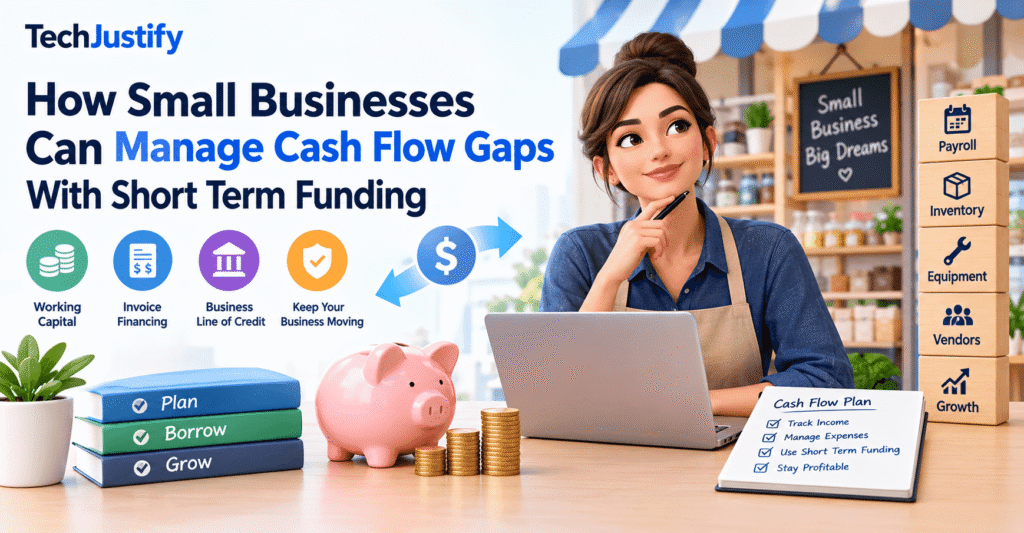
Cash flow gaps are common in small businesses because money often leaves the business before customer payments arrive. Owners may need to cover payroll, restock inventory, repair equipment, or pay a vendor while waiting for invoices to clear. In those situations, comparing alternative lenders for working capital can be one part of a broader plan, alongside reviewing reserves and reducing avoidable expenses.
Short-term funding can be useful when it supports a defined business purpose, rather than covering an ongoing problem without a solution. The goal is not to access the largest available amount. It is to use the smallest practical amount for the shortest reasonable period while protecting the business’s ability to meet its regular obligations.
Table of Contents
Why Cash Flow Gaps Happen Even in Healthy Businesses
Profit and available cash are not the same thing. A contractor may complete a project, send an invoice, and record revenue, but the customer may not pay for 30 or 45 days. Meanwhile, payroll and material costs may be due this week. Seasonal businesses can face a similar issue when inventory and staffing costs rise before their busiest sales period begins.
Unexpected equipment repairs, delayed customer payments, and large supplier orders can also create a short-lived gap. The important question is whether the shortage is temporary and tied to money that is likely to arrive, or whether it reflects a deeper issue, such as recurring losses, declining demand, or expenses that exceed normal revenue.
Start With a Cash Flow Check
Before applying for financing, map the business’s expected cash flow for the next 13 weeks. A simple forecast can show the size of the gap, its likely end date, and whether borrowing is actually necessary.
- List expected customer payments and sales by week.
- Record fixed costs, including rent, payroll, insurance, software, and loan payments.
- Mark flexible expenses that can be postponed, reduced, or renegotiated.
- Review unpaid invoices and confirm expected payment dates with customers.
- Calculate the minimum amount required to keep essential operations moving.
Match the Funding Type to the Need
- Cash reserves: May be appropriate for a small, brief shortfall if using savings will not leave the business vulnerable.
- Business credit card: Can fit smaller purchases that can be repaid quickly under the card’s terms.
- Term loan: May suit one planned expense with a known amount and a defined repayment schedule.
- Revolving line of credit: Can be useful for repeated or uncertain working-capital needs.
- Invoice financing: May help a business access funds tied to outstanding customer invoices.
How a Revolving Credit Line Works
A revolving business credit line generally provides a credit limit rather than a lump-sum loan. The business draws only what it needs, repays according to the agreement, and may regain access to repaid funds if the account remains in good standing. Review the basics of the business line of credit before comparing offers.
When evaluating a revolving option, focus on the credit limit, the amount drawn, the cost charged on the outstanding balance, the repayment schedule, and whether repayment restores available credit. A line designed for occasional operating expenses may not be a good fit for a long-term expansion project.
Review the Real Cost Before Signing
An advertised rate alone does not show the full borrowing cost. Ask for clear written terms and compare offers using the same dollar amount and repayment period.
- Interest rate, annual percentage rate, or other stated financing cost
- Origination, draw, maintenance, late-payment, and renewal fees
- Weekly, biweekly, or monthly payment requirements
- Prepayment rules and the total repayment amount
- Personal guarantee, collateral, or lien requirements
- Whether payments remain manageable during a slower sales month
Build a Repayment Plan Before Taking Funds
Connect every borrowing decision to a specific repayment source. For example, funds used to buy materials for a confirmed project should be repaid from the customer payment associated with that project. Funds used for a seasonal inventory order should be tested against conservative sales expectations, not the most optimistic forecast.
- Name the expense the funds will cover.
- Estimate when it should produce revenue or savings.
- Reserve money for required payments before discretionary spending.
- Test the plan against a delayed invoice or a slower month.
- Review the balance weekly until it is paid down.
Improve Cash Flow Before Borrowing
Funding is only one way to address a gap. Send invoices promptly, offer straightforward payment options, request deposits for larger projects, and follow up on overdue balances with a clear schedule. Review recurring subscriptions, vendor terms, and inventory reorder points to identify cash that may be unnecessarily tied up.
Delayed payments can put real pressure on smaller firms, particularly when operating costs continue regardless of when an invoice is paid. Recent reporting on the toll of late payments on small businesses illustrates why owners should monitor receivables closely and communicate early with customers whose payments are past due.
Documents to Prepare Before Applying
- Recent business bank statements
- Profit-and-loss statement and balance sheet
- Accounts receivable report
- Business tax returns and registration details
- Owner identification and relevant credit information
Questions to Ask a Financing Provider
- What is the total cost if the balance is repaid early?
- How often are payments due, and can the payment amount change?
- Are there fees for draws, maintenance, late payments, or unused funds?
- Is a personal guarantee or collateral required?
- Can the business draw funds more than once, and how does repayment affect future access?
Read Also:- B2B Social Media Marketing: Strategies for Generating Business Leads in 2026
FAQs About Short-Term Business Funding
What is the best choice for a seasonal business?
A flexible option may help when expenses rise before seasonal revenue arrives, but the expected profit from the season should comfortably support the repayment plan and financing cost.
Is a line of credit better than a term loan?
Neither is automatically better. A line of credit may fit changing, recurring expenses, while a term loan may fit a one-time purchase with a fixed repayment plan.
How much should a business borrow?
Borrow only the amount tied to a clear operating need and a realistic repayment source. Smaller balances are often easier to manage than the maximum amount available.
What if revenue drops after borrowing?
Review expenses immediately, protect funds needed for required payments, and contact the provider early if repayment may become difficult.
A Simple Decision Framework
Define the gap: Identify the amount needed and the dates involved.
Check alternatives: Review reserves, deposits, collections, and expense reductions.
Choose the structure: Match the product to the purpose and repayment timing.
Compare full costs: Include fees, payment frequency, and guarantee requirements.
Stress-test repayment: Make sure the plan can withstand a slower month.
Conclusion
Short-term funding can help a small business bridge a temporary cash flow gap, cover essential operating expenses, or manage unexpected costs. Still, it works best when supported by a clear financial plan. Before choosing a funding option, owners should determine the amount they need, specify how the funds will be used and estimate when they can reasonably repay them.
Comparing the full cost of borrowing, including interest rates, fees, and repayment terms, can help them understand the financial commitment involved. It is also important to match repayment schedules with expected revenue and account for possible delays in customer payments or slower sales.
Careful borrowing can help keep daily operations moving, maintain access to essential supplies, and address temporary financial pressures without creating a larger problem later. By treating short-term funding as a targeted solution rather than a substitute for cash flow management, small businesses can make more informed decisions and protect their financial stability.
Lokesh Sharma is a digital marketer and SEO expert at TechJustify with a keen interest in emerging technology trends including AI, cybersecurity, and digital marketing tools for more than 5 years. He writes clear, actionable articles for tech enthusiasts and business leaders, simplifying complex topics like VPNs, automation, and generative AI.